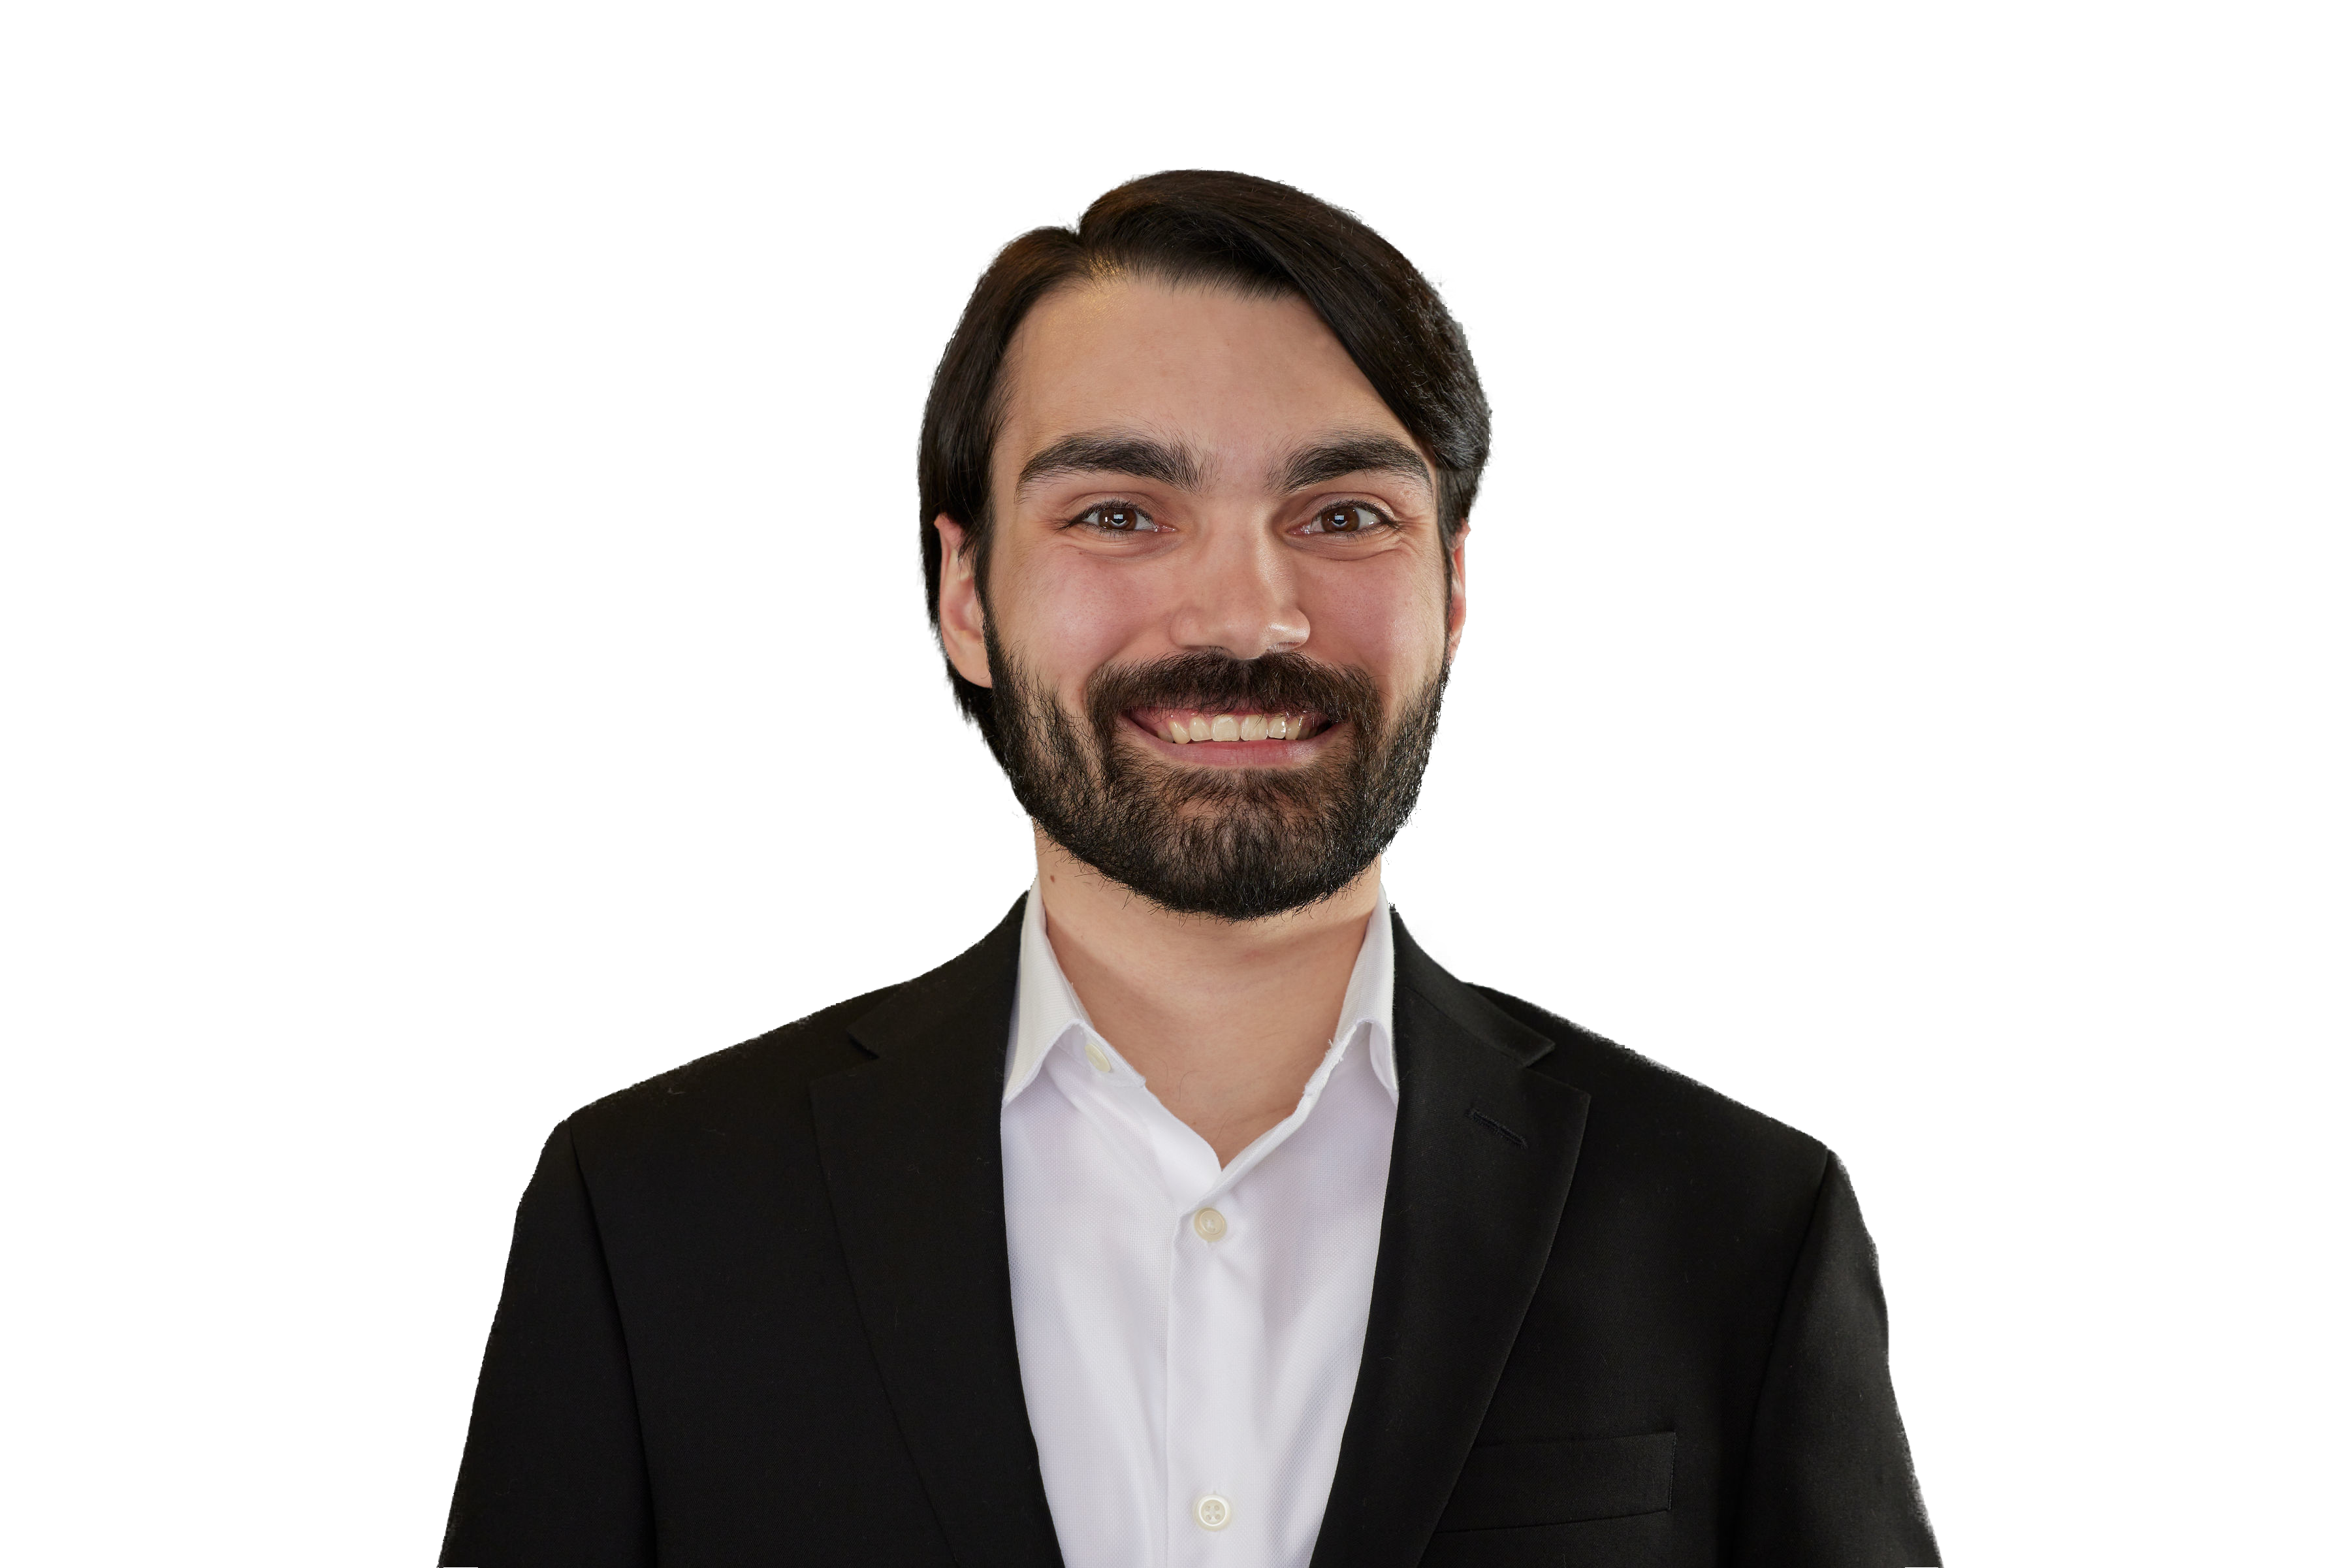
Born and raised in the midlands of South Carolina, I moved to Clemson to pursue a Bachelor's of Science in Psychology. After graduating, my wife and I settled down in Simpsonville while she completed her master’s degree and, I began work as a mortgage loan processor. A few years later, I completed training, passed the national exam and became a licensed mortgage broker and, to date, have been directly involved with well over 300 mortgage transactions and counting!
My name is Grayson Ballentine and I am a mortgage broker dealing in both residential and commercial spaces!
I've helped folks buy their first home and I've helped folks expand their portfolios into the 8-digit marks using some exceptional offerings from some banks we may all know and love as well as some we may have never heard about!
Feel free to check out some of those products, below!
Residential Products break down into two major groups, really: Conventional and Government, what we call "Govvies." The Conventional loan program is exactly as it sounds: conventional. It's the product most folks shoot for and are familiar with, sometimes, without even realizing it! Govvies are broken down into three major products known as the FHA, USDA, and VA home loans. These are loans that are sponsored/insured/guaranteed by the government so long as the proper qualifications are met per the program's guidelines.
FHA: The FHA Home Loan is what most people know as that "First Time Homebuyer Program" as the program, historically, has been used for first-time homebuyers who needed looser debt-to-income constraints, a lighter down payment requirement, lower credit scores than what may qualify for other programs or a mix of it all. My personal opinion? The only loan better than an FHA loan is a VA loan!
VA: The VA Loan Program is a program offered by the Office of Veteran's Affairs and is only offered to servicemembers and their surviving spouses that qualify. Borrowers without sufficient service records, war-time deployment(s), and family members (excluding surviving spouses) need not apply. The VA Program is designed to, and has historically, been used to make the path to homeownership less stressful and far more secure for those who sacrificed so much for our great nation!
USDA: The USDA Rural Guarantee Program is what most folks know as the "Ag" or "Agriculture" loan. When the program was first introduced, it was marketed to farmers and families who lived more rurally than not to allow them more readily available access to funding for more farmland that, in turn, helps to feed our nation! While, historically, the USDA program was used to make farmland more accessible to those willing to accept the challenge, today, the program mainly sees utility in urbanizing, or populating, rural areas by way of incentivizing landownership and reducing the unnecessary risks faced by families who live in or are moving into these areas.
Commercial products tend to also break down into two major groups: residential-based commercial ventures and commerce-based commercial ventures.
Commerce-Based Commercial Products are products designed for investors, business owners, and entrepreneurs who may have a history of owning and operating commercial properties or businesses, may be interested in acquiring more, moving from one to another, looking to expand their operations, footprint, or maybe the hometown startup that's looking to land their first brick and mortar.
Commercial products are able to cast a wider net on behalf of its clients to include things like lines of credit, drawn down lines, working capital, bridge loans, and so much more that may not suit the needs of the average homebuyer but open multiple opportunities for everyone from the astute Wall Street investor to leverage their position without overextending themselves in the pursuit to the boutique old lady Smith wants to purchase and renovate down on Main.
Residential-Based Commercial Products is just a fancier way of saying Investment Products; more on those, below!
Real Estate-Based Investment Products are mainly as they sound: an individual or company has decided to expand its portfolio into the real estate sector and are seeking financing depending on what their plan for the property is. Simply put, these are products where the client has no intention on living in the home as their place of residence. They may chose from a number of different options when pursuing an investment loan and having the right product to suit your needs is a majority of the battle!
Fix and Flip are scenarios where the investor is seeking to acquire a property that may not be in the best of condition, in need of renovations, or just a little TLC to brighten it back up.
Whatever the case may be, a Fix and Flip product would be utilized by an investor that intends on renovating the home or "fixing it up" to then turn around and sell it or "flip it" for a profit.
Renovate and Rent is very similar to the Fix and Flip, above; however, as the name indicates, after the renovation, it's the client's intention to retain, or keep the property, to be rented 0ut at a fair market rate.
These two products usually open a working line of capital for the contractor to draw from while they do the renovations or repairs that, depending on the end-use for the property (be it flipped or rented), get rolled back into the loan to be paid over time or paid on sale in the event of a flip.
Bridge Loans help to "bridge" ownership of one property to another. Let's say you were selling one of your strip malls to buy a nicer one downtown but you needed an additional $100,000 to close on the newer, nicer one. You won't have the money until your original one sells so in comes the Bridge Loan to "bridge" the gap between the two properties. You would close on the new one, pay on the bridge loan as agreed and, once your original property sells, you pay back the bridge and pocket the difference!
Portfolio Loans are sometimes lines of credit that a bank may open on behalf of an established and, historically, well-performing investor. These credit lines will be secured by what is called the client's "portfolio" of properties. These are not common loans to encounter in the wild but are formidable offerings nonetheless when compared to Hard Money!
Construction Products are probably the ones we are all most familiar with be it one of the nation's top homebuilders putting in a tract near you or your one-off builds done off the beaten path on your own plot of land tucked away from any neighbors or Homeowner's Associations!
These products allow a builder or contractor access to working capital so they aren't coming directly out of pocket for things like materials during the build process. At a near-no-cost to them, they are able to draw what they need, per the approved plans, to build you the home of your dreams to your exact specification!
When it's nearly complete, we'll get your loan drawn up to the same exacting specifications, all of our I's dotted and our T's cross, over to the attorney's office for some signatures and off to your brand new home!
Construction products may include building to rent or sell aspects as well so investors need apply also - these products aren't just for homeowners!
Click the button below to be taken to our secure portal!